Security First Future: Safeguarding Finances with Digital Banking
How digital banks and payment providers protect your company's money and data, and the practical security habits that close the remaining gaps.
 5 min read
Most businesses now run their finances entirely online: account opening, payments, payroll and reconciliation all happen through apps and web dashboards. That convenience raises a fair question: how safe is your money in a digital account, and what can you do to keep it that way?
This guide explains the security measures digital banks and payment providers use, the habits that protect you on your side, and how regulation protects your data and funds.
The security landscape of online banking
Online financial services face constant threats: phishing, account takeover, malware, social engineering and payment fraud. Providers defend against them with several layers of protection.
- Encryption in transit: connections between your device and the provider use Transport Layer Security (TLS), so data cannot be read or altered if intercepted.
- Encryption at rest: stored customer data is encrypted, and access is limited to systems and staff that need it.
- Secure infrastructure: firewalls, network segmentation, access controls and continuous monitoring protect servers and databases.
- Independent testing: regulated providers run penetration tests and audits, and card businesses must comply with the Payment Card Industry Data Security Standard (PCI DSS).
Multi-factor authentication
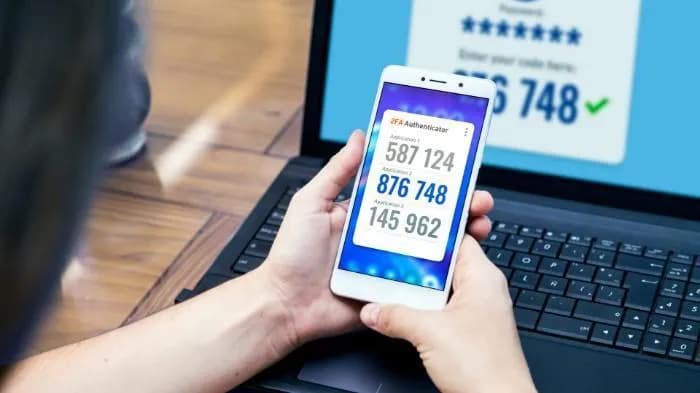
A password alone is not enough. Multi-factor authentication (MFA) requires at least two different proofs of identity: something you know (a password or PIN), something you have (a phone or hardware key) and something you are (a fingerprint or face scan). In the UK and EU, strong customer authentication rules require this for logging in and for most payments.
The strongest options are app-based approvals, hardware security keys and passkeys, which are tied to your device and resist phishing. One-time codes sent by SMS are better than nothing but can be intercepted through SIM-swap fraud, so use an authenticator app or passkey where your provider supports it.
Fraud detection and prevention
Digital banks and electronic money institutions monitor transactions in real time. Machine learning models compare each payment with your normal behaviour, such as amounts, payees, devices, locations and timing, and flag or block anything unusual. Other common controls include:
- Payee name checks, which warn you if the account name does not match the details you entered.
- Delays and extra confirmation for first payments to new payees.
- Configurable transaction and card limits.
- Instant alerts for logins, new devices and payments.
The fastest-growing threat to businesses is authorised push payment fraud, where criminals trick staff into sending money themselves, often by impersonating a supplier or a director. Technology helps, but process is your best defence.
User practices for enhanced security
- Use strong, unique passwords for every financial account, stored in a password manager.
- Enable MFA everywhere, preferably with an authenticator app, hardware key or passkey.
- Verify payment changes by phone. If a supplier emails new bank details, confirm them using a number you already have, not one in the email.
- Use dual approval for payments above a set amount, and give each team member only the access they need.
- Keep devices and apps updated and turn on automatic updates.
- Avoid public Wi-Fi for banking, or use a trusted VPN.
- Be wary of urgency. Real banks never ask for your password or one-time codes, and never ask you to move money to a "safe account".
- Lock your devices with a PIN or biometrics and enable remote wipe.
- Review transactions regularly and report anything unusual to your provider immediately.
- Train your team on phishing and invoice fraud at least once a year.
Privacy and data protection
Financial institutions handle sensitive personal and company data, and several frameworks govern how they do it:
- GDPR and UK GDPR: require lawful, transparent processing of personal data, appropriate security, and notification of serious breaches.
- PCI DSS: sets security standards for anyone storing, processing or transmitting card data.
- Anti-money laundering rules: require providers to verify customers and monitor transactions. The identity checks you complete at onboarding are part of what keeps criminals out of the system.
- Operational resilience rules: in the EU, the Digital Operational Resilience Act (DORA) requires financial firms to manage ICT risk and report major incidents.
How your funds are protected
Protection depends on the type of provider. Deposits at a licensed bank are usually covered by a national deposit guarantee scheme up to a set limit. Electronic money institutions do not lend out client money; they must safeguard it, keeping it separate from their own funds, usually in segregated accounts at banks. Ask your provider which model applies before you hold large balances. Our article on traditional banking v digital payment solution providers explains the difference in more detail.
How WeForm approaches security
WeForm runs company formation fully online, including identity verification, electronic signing with WeFormSign and secure storage of corporate documents in your client dashboard. You can read more on our security page. Every package includes assistance with opening a payment account with supported banks, electronic money institutions and payment providers, typically within 3 to 14 business days. See our banking services or start your application.
FAQ
What is digital banking?
Managing accounts and payments through online platforms and mobile apps instead of a branch. It covers online banking, mobile banking and accounts with electronic money institutions.
Is digital banking safe for a business?
Regulated providers use strong encryption, authentication and monitoring. Most losses happen through social engineering, so your own processes, such as payment verification and dual approval, matter as much as the provider's technology.
What should I do if I suspect fraud?
Contact your provider immediately using the number in the app or on its website, freeze cards or access if possible, change your passwords and report the incident to the police or national fraud authority.
How do I open a digital business account?
Choose a provider that supports your jurisdiction and business model, prepare your company documents and owners' identification, and complete online verification. Read about the difficulties of opening a bank account, the digital banking trends for 2026 and the benefits of digital banking before you apply.