Digital Banking Trends for 2026 and Beyond
The digital banking trends shaping 2026, from AI and instant payments to remote onboarding and fraud controls, and what they mean for business owners.
 5 min read
Digital banking keeps changing how companies open accounts, move money and manage cash. For founders running international businesses, several of these changes are practical rather than theoretical: faster onboarding, cheaper cross-border payments and better tools for controlling spending and fraud.
Below are the digital banking trends that matter most for business owners in 2026, and what to do about them.
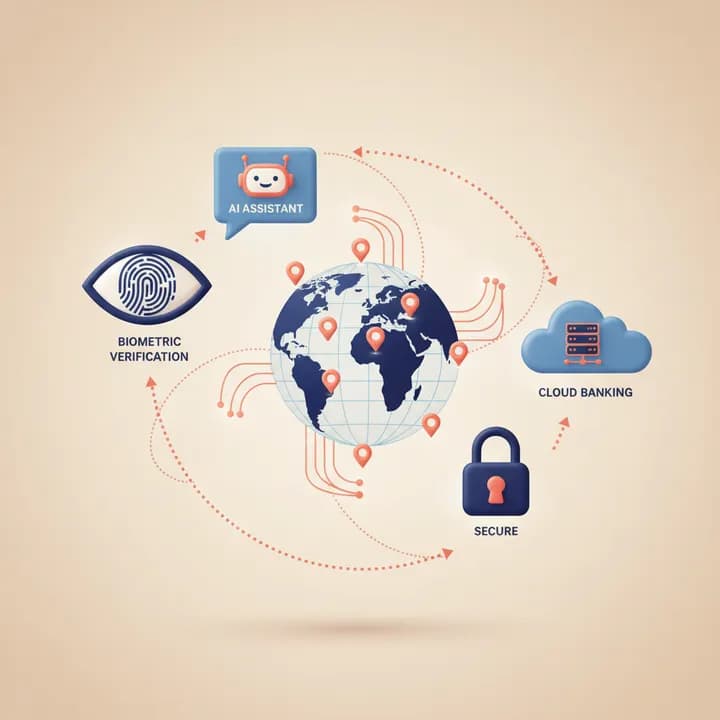
Key digital banking trends 2026 you should know
AI-powered banking and cash-flow insight
Banks and fintech providers increasingly use AI to categorise transactions, forecast cash flow, flag unusual spending and answer routine questions through chat assistants. For a small company, this means less manual bookkeeping and earlier warning of cash shortfalls. Treat AI insights as a starting point and keep a human check on anything that affects tax or compliance.
Instant payments become the default
Real-time payment schemes now cover most major markets. In the EU, the Instant Payments Regulation requires payment providers in the euro area to offer instant euro credit transfers at no higher price than standard transfers, together with a check that the payee's name matches the account. The UK has run Faster Payments for years and uses Confirmation of Payee. For businesses, faster settlement means better cash flow and fewer misdirected payments.
Open banking and API connections
Open banking lets you securely share account data with accounting software, lenders and payment tools, and lets customers pay directly from their bank account. Business accounts with good APIs and integrations save hours of reconciliation each month. When comparing providers, check which accounting and e-commerce platforms they connect to.
Fully digital onboarding
Account opening is now largely remote: identity verification with a selfie and passport scan, electronic signatures and digital submission of company documents. Newly incorporated companies can often open an account without visiting a branch, provided their documents are consistent and the business activity is clearly explained. Our guide on the difficulties of opening a bank account explains what usually slows applications down.
Multi-currency accounts as standard
Holding, receiving and paying in several currencies from one account is no longer a premium feature. For companies with international clients or suppliers it removes double conversion fees and gives local account details in key markets. See our step-by-step guide to opening a multi-currency business account.
Embedded finance
Payments, financing and insurance are increasingly built into the software businesses already use, such as e-commerce platforms, marketplaces and invoicing tools. That reduces the number of logins and accounts you manage, but it also spreads your money across more providers, so keep a clear view of where funds are held and how they are protected.
Stronger fraud prevention and regulation
Authorised push payment scams and account takeover remain the biggest risks for businesses. Providers are responding with behavioural analytics, payee name checks, transaction monitoring and stronger customer authentication. Regulation is moving in the same direction: in the EU, the Digital Operational Resilience Act (DORA) has applied to financial firms since January 2025, and the payment services rules are being updated. Our article on safeguarding finances with digital banking lists the controls you should switch on.
Cloud-based core banking and automation
Many banks and electronic money institutions now run on cloud-based core systems and automate back-office tasks such as compliance checks and payment processing. For customers, this usually shows up as faster product updates, quicker payment processing and more reliable service.
Digital assets under clearer rules
Tokenised money and stablecoins are moving from experiment to regulated product. The EU's Markets in Crypto-Assets Regulation (MiCA) now applies in full, and several central banks are testing digital currencies. For most small businesses this is still a watch item rather than an action item, but it is worth understanding what your provider supports.
What these trends mean for business owners
- Open the right account early. A business account that supports your currencies, payment methods and integrations saves work later. Our comparison of traditional banking and digital payment solution providers explains the trade-offs.
- Keep your documents consistent. Remote onboarding depends on clean company documents and a clear description of expected transactions.
- Review payment acceptance. Customers expect cards, wallets and instant bank payments. See what's the best payment solution for your business.
- Turn on every security control your provider offers, including multi-factor authentication, approval workflows and payee checks.
How WeForm helps
WeForm forms companies in six jurisdictions: the United Kingdom, Hong Kong, Seychelles, the Marshall Islands, Costa Rica and IFZA Dubai. The whole process runs online, including identity verification, electronic signing and access to your corporate documents in the client dashboard. Every package includes assistance with opening a payment account with supported banks, electronic money institutions and payment providers. Account opening typically takes 3 to 14 business days, and newly incorporated companies can apply. Approval is decided by the financial institution, not guaranteed.
Explore our banking services and payment solutions, compare all jurisdictions, or start your application.
FAQ
What is the biggest digital banking trend for businesses in 2026?
For most small businesses, the practical changes are instant payments with payee checks, fully remote onboarding and AI-assisted cash-flow tools.
Can a newly formed company open a digital business account?
Yes. Many digital providers accept newly incorporated companies, subject to their own due diligence on the owners, the business model and the jurisdiction.
Are digital banks and EMIs as safe as traditional banks?
They are regulated, but protection differs. Bank deposits are usually covered by a deposit guarantee scheme, while electronic money institutions must safeguard client funds separately from their own money. Check which applies to your account.